A salary relationship
Personal accident cover can be introduced within a banking relationship, with clear insurer terms and an explicit customer choice.
Explore the salary exampleFor distributors
Build an insurance proposition around the relationships you already have. Connect your channels with approved insurers and guide customers from their first choice through ongoing service.
Insurance in a familiar context
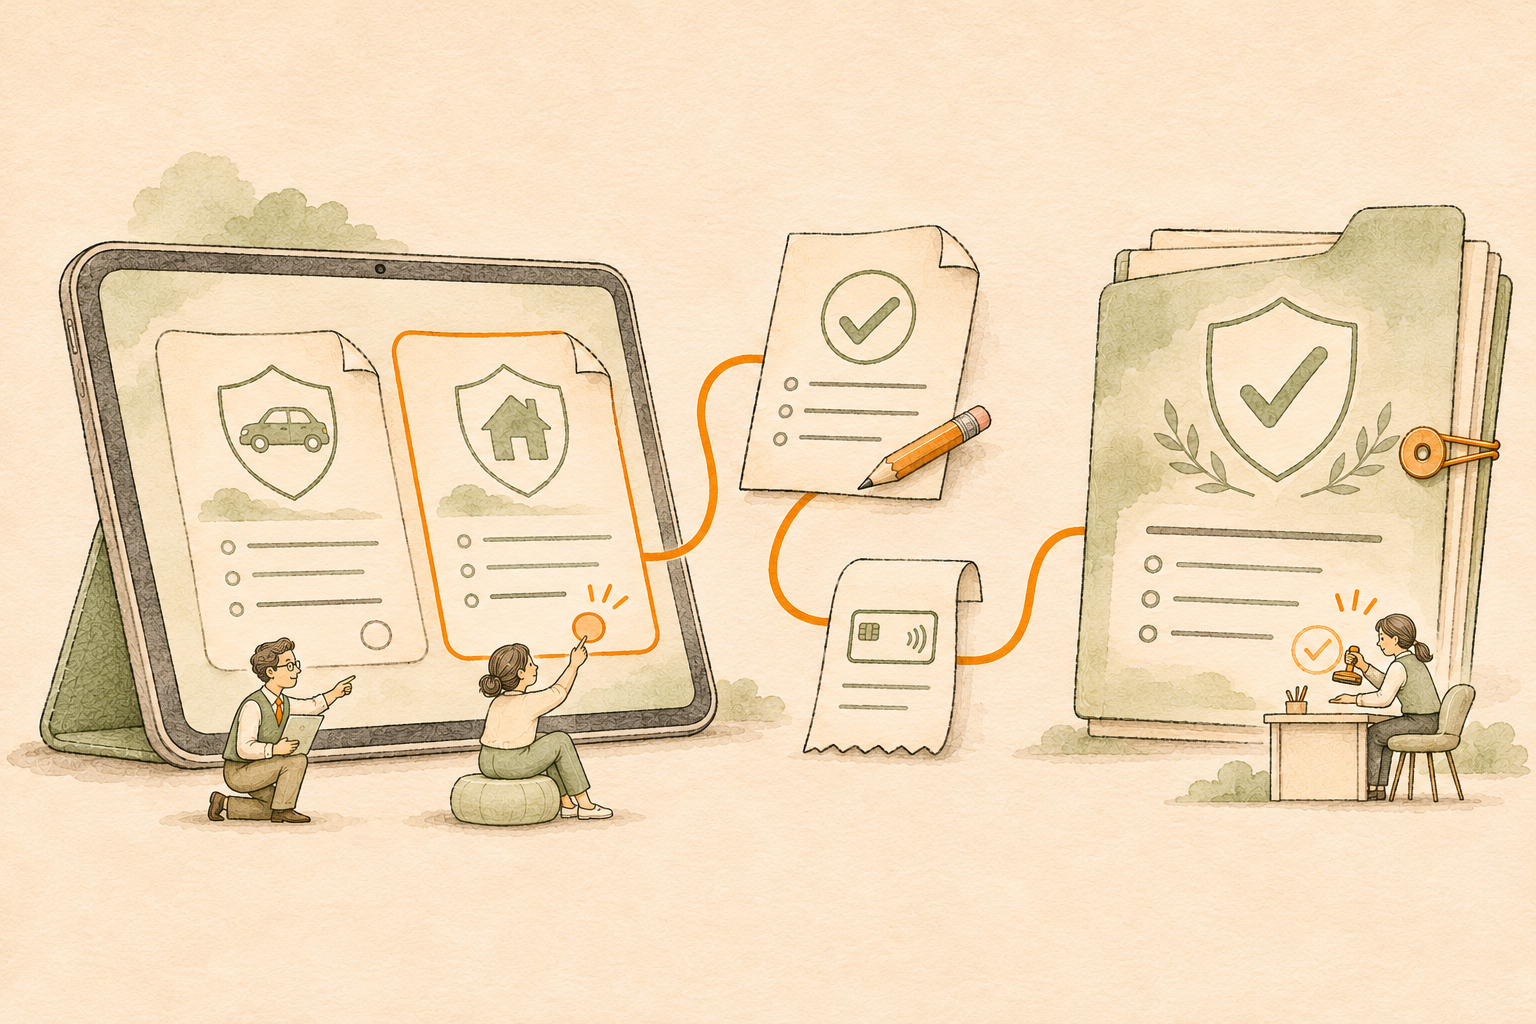
A proposition works when the product, customer need and channel belong together. These examples are illustrative and depend on approved insurer arrangements.
Personal accident cover can be introduced within a banking relationship, with clear insurer terms and an explicit customer choice.
Explore the salary exampleAn approved hospital cash proposition can be introduced in a wallet journey, with the customer reviewing the offer before giving consent.
Explore the wallet exampleAn approved credit life proposition can be connected to a loan journey. The insurer provides the terms and confirms policy issuance.
Explore the loan exampleYour authorised staff can help customers understand available propositions and initiate sales or service requests within your channel.
See the customer experienceOne channel. Approved insurer relationships.
Connect with one insurer or several under approved partnerships. When more than one offer is available, customers can review the options before selecting their insurer and cover.
Your team coordinates the customer interaction. The insurer provides quotations, issues policies and makes insurance decisions.
Illustrative distributor view
Distributor connectivity
Approved apps, websites and assisted sales channels send customer events and requests into Connect. The common controller routes the work and returns progress and insurer outcomes to the originating experience.
An agreed channel sends the event, approved product context and permitted customer information.
The configured connection identifies the organisation and applies the permitted scope.
Connect records the next task, responsible role and insurer response.
Agreed callbacks or status handling bring progress and the final result back to the customer channel.
A relationship beyond the sale
Help should stay linked to the policy and the partnership that served the customer.
Customers can access issued policy information and initiate service, claim or cancellation requests through the agreed experience. Your team can help them provide the details and evidence needed for insurer review.
Connect carries progress and outcomes across the partnership. The insurer retains authority over the insurance decision.
Explore policy servicing
Your questions
Clear answers before you plan your partnership.
No. Your organisation owns the customer channel and relationship. The insurer controls products, quotations, issuance and insurance decisions. The partnership defines the permitted roles and activities.
Where the approved partnership includes several insurers and available offers, the customer can review those options before selecting cover. A single-insurer proposition remains a valid journey.
Payment to the distributor and insurer issuance are separate steps. The customer should see a pending status until the insurer confirms policy issuance. Cover details and timing follow the issued policy terms.
The distributor remits the full premium to the insurer. The insurer pays commission separately to the distributor on the agreed terms and schedule. Commission is not deducted from premium remittance.
The proposition depends on the approved products, customer take-up, partnership terms and service delivery. Connect supports the operating model; it does not guarantee revenue or conversion outcomes.
Let’s shape the opportunity
Tell us about your channels, customer moments and intended insurer relationships.